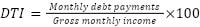
Applying for a personal loan is typically very quick, but getting a good rate is a matter of planning. Simply meeting the basic criteria won’t necessarily get you the amount you’re after or a good rate. Checking the eligibility criteria, gathering the correct documentation and having a good look at the fees on the loan will save you time and avoid any unnecessary credit checks.
Personal Loan Requirements to Check Before You Apply
Check Where Your Credit Score Stands
Your credit score gives lenders a quick idea of how you’ve managed borrowed money. In the US, FICO scores typically range from 300 to 850. A score of 670 or more is considered good, although each lender sets its own criteria. A higher score can improve your odds of approval and help you qualify for a lower interest rate.
You can acquire free reports from Equifax, Experian and TransUnion via AnnualCreditReport.com.
Pay particular attention to:
- Errors in your report
- High credit card balances
- Recent credit applications
- Older negative marks
If your score could be better, try paying down your credit card balances, fixing any mistakes on your report and making sure your current accounts are up to date before you apply.
Gather Your Identification and Application Documents
A lender will always want to confirm that you are who you say you are and that the financial details you’ve provided are correct. This is no different with an online application. You’ll be asked for identification and may be required to upload supporting documentation. Obtaining a loan without identification is very difficult, but some lenders accept non-traditional forms of ID (a birth certificate and a copy of your SS card).
Documents or information to prepare
Identity – Government-issued driver’s license, state ID or passport
Social Security number – Your Social Security card
Address – Current address and, if requested, a utility bill, lease or mortgage statement
Employment – Employer details, recent pay stubs or employment verification
Income – W-2s, 1099s, tax returns, pension statements or bank statements
Self-employed applicants may need tax returns and bank statements covering a longer period than salaried applicants. Be cautious of anyone promising guaranteed approval when you’re obtaining a loan without identification checks, especially if they request you to pay an upfront fee or share sensitive information through an unsecured channel.
Confirm Your Income Meets the Lender’s Requirements
A lender needs evidence that you can repay the loan without falling behind on your other bills. A salary that meets the lender’s minimum doesn’t mean you can comfortably afford the monthly payment. Your rent, utilities, groceries, insurance and other essential expenses still need to fit into your budget. Your income helps answer that question, but there isn’t one universal minimum salary.
Calculate Your Debt-to-Income Ratio
Your debt-to-income ratio (DTI) shows how much of your gross monthly income is spent on monthly debt payments. Lenders use it to judge how much room you have for another financial obligation.
Your monthly debt payments include obligations such as mortgage or rent-related debt, auto loans, student loans and minimum credit card payments. A ratio below 36% is often a useful target, but some lenders accept higher ratios, while others have stricter limits.
Check the Origination Fee and Total Borrowing Cost
Some lenders demand an origination fee to process and arrange the loan. This fee may be deducted from the money disbursed. Origination fees can range from 1% to 10% of the loan amount, with some lenders charging no fee at all.
Before accepting an offer, review these costs:
- Origination fee
- Annual percentage rate: that’s the interest rate plus certain loan fees. It’s a useful basis on which to compare offers.
- Monthly payment
- Loan term
- Late payment and other fees
- Prepayment terms
Conclusion
Before submitting a personal loan application, take a few minutes to check the details that could affect both approval and affordability. Review your credit reports for errors, calculate your debt-to-income ratio, gather documents and compare the APR, origination fees and repayment terms of lenders you qualify with. If your credit score needs work or the proposed monthly payment would stretch your budget, waiting and improving your financial position may save you money in the long run.